Understanding the health insurance coinsurance definition can help you predict what you will owe when you visit a doctor, undergo a medical procedure, or receive a hospital bill. Many Americans know their monthly health insurance premium, but they are less familiar with the percentage they may need to pay when they actually use their coverage.
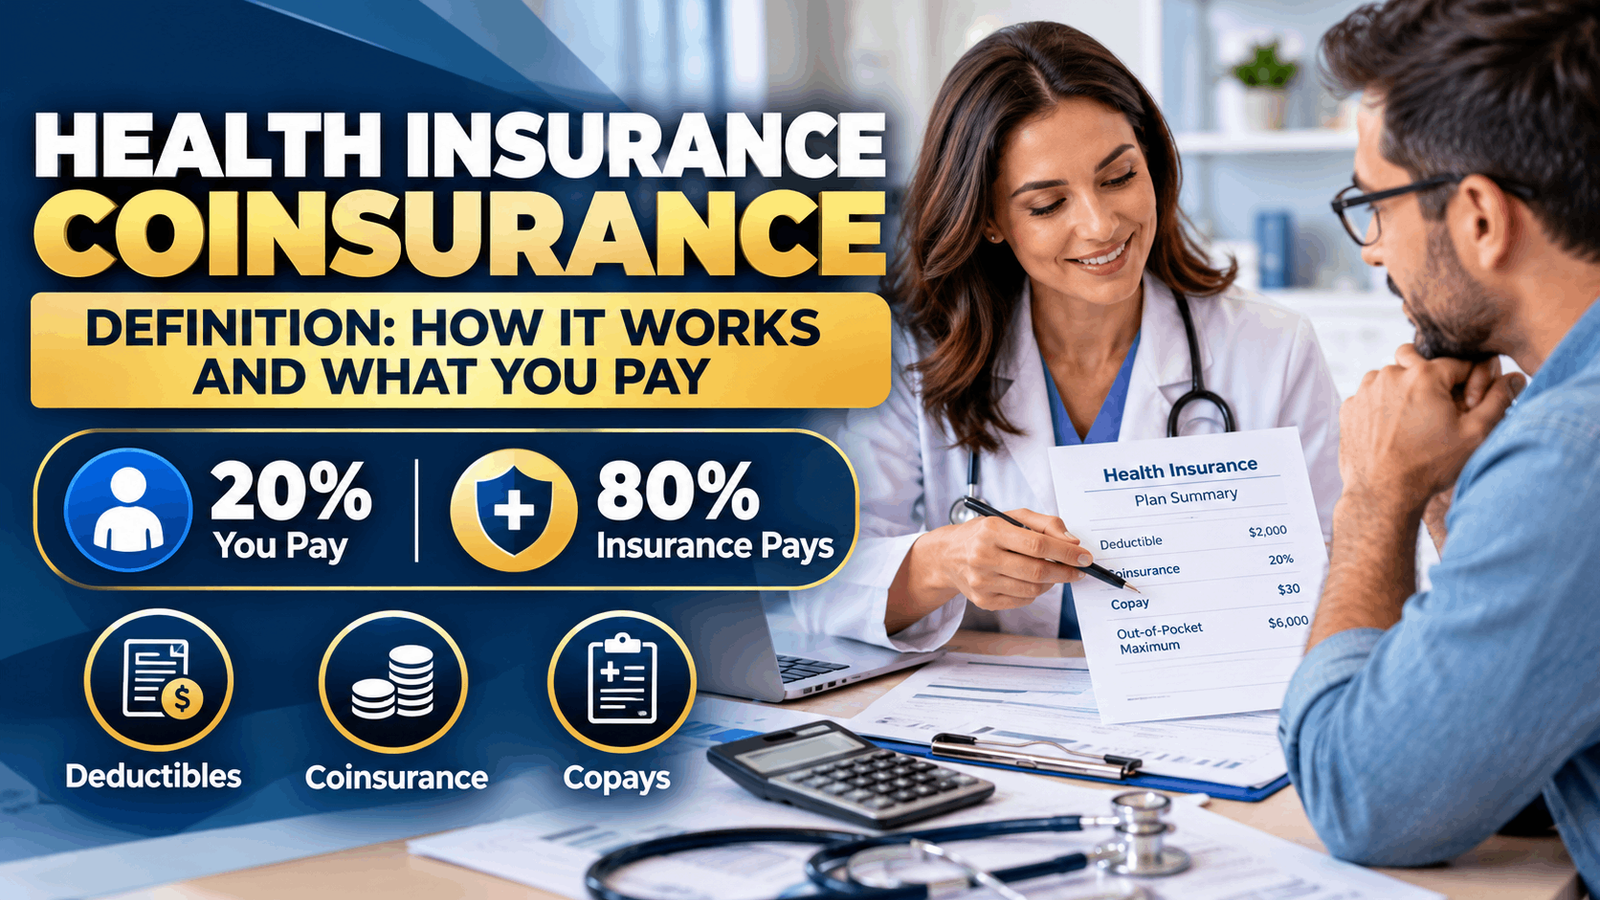
In simple terms, coinsurance is your percentage of the allowed cost of a covered healthcare service. A plan with 20% coinsurance generally means you pay 20% and your insurer pays 80% after you meet the applicable deductible. However, your actual responsibility also depends on your provider network, the type of service, and your out-of-pocket maximum.
This guide explains the health insurance coinsurance definition with practical U.S. examples, clear calculations, and comparisons with deductibles and copays so you can understand what you may pay before choosing a health plan.
Health Insurance Coinsurance Definition: What It Means
The health insurance coinsurance definition is the percentage of a covered medical service’s allowed amount that you pay under your health plan. Unlike a fixed copay, coinsurance changes with the cost of the service.
For instance, a policy with 20% coinsurance usually divides an eligible $1,000 expense into a $200 patient payment and an $800 insurance payment, assuming the relevant deductible has been met. The percentage applies to the allowed amount determined under the plan, not necessarily the provider’s original billed charge.
According to HealthCare.gov’s official coinsurance glossary, coinsurance is the percentage of costs you pay for a covered healthcare service after paying your deductible.
The health insurance coinsurance meaning is therefore about cost sharing. Your insurer covers its share of eligible expenses, while you remain responsible for the percentage specified in your plan documents.
How Health Insurance Coinsurance Works
To understand how health insurance coinsurance works, follow the path of a typical covered medical claim:
- You receive a healthcare service covered by your plan.
- The provider submits a claim to your insurance company.
- The insurer determines the service’s allowed amount and checks your deductible status.
- Any remaining applicable deductible is applied first.
- Coinsurance is calculated on the eligible amount subject to percentage-based cost sharing.
- You receive an explanation of benefits showing the insurer’s payment and your estimated responsibility.
An explanation of benefits is not itself a bill. Compare it with the provider’s statement, and contact your insurer if the amounts do not match.
The health insurance coinsurance definition is especially important here because the percentage may be applied to a negotiated in-network rate rather than the provider’s full charge.
Health Insurance Coinsurance Definition With a $1,000 Bill
Suppose a healthcare provider bills $1,300 for a covered service. Your insurer’s allowed amount is $1,000, your deductible has been met, and your coinsurance is 20%.
| Item | Amount |
|---|---|
| Provider’s original bill | $1,300 |
| Insurer’s allowed amount | $1,000 |
| Your 20% coinsurance | $200 |
| Insurer’s 80% share | $800 |
In this simplified in-network example, you owe $200 rather than 20% of the original $1,300 charge. The difference between billed and allowed amounts is one reason to review network status and plan rules carefully.
Health Insurance Coinsurance After Deductible
A deductible is the amount you pay toward certain covered services before your health plan begins sharing those costs. Most plans apply coinsurance after the relevant deductible has been satisfied, although some services follow different rules.
For example, some preventive services are covered without cost sharing when you meet the plan’s eligibility and in-network requirements. Other benefits may use a copay or separate deductible.
The health insurance coinsurance definition does not mean you automatically pay only your stated percentage from the first medical visit of the year. If a service is subject to an unmet deductible, your initial payment can be much higher.
Example: A $5,000 Medical Bill With a Deductible
Imagine you have a $2,000 deductible, 20% coinsurance, and no previous payments toward the deductible. You receive an eligible in-network service with an allowed amount of $5,000.
First, you pay $2,000 to satisfy the deductible. That leaves $3,000 subject to coinsurance. Your 20% share of $3,000 is $600.
| Calculation | Amount |
|---|---|
| Allowed cost | $5,000 |
| Deductible you pay | $2,000 |
| Amount remaining | $3,000 |
| Your coinsurance (20% of $3,000) | $600 |
| Total you pay | $2,600 |
| Insurance pays | $2,400 |
If you had already paid $1,700 toward your deductible, only $300 would remain. For the same $5,000 allowed amount, you would then pay the remaining $300 plus 20% of $4,700, or $940, for a total of $1,240. These examples assume no other coverage limits or cost-sharing requirements.
Health Insurance Coinsurance vs Deductible
The distinction between health insurance coinsurance vs deductible matters because both affect your medical bills, but they work differently.
A deductible is generally a dollar threshold you must satisfy for certain services. Coinsurance is a percentage of the allowed cost that you pay when that form of cost sharing applies. A copay is usually a fixed amount for a particular service.
| Feature | Deductible | Coinsurance | Copay |
|---|---|---|---|
| How it is measured | Dollar amount | Percentage | Usually a fixed dollar amount |
| Example | $2,000 annually | 20% of allowed cost | $30 office visit |
| When it applies | Depends on benefit rules | Often after deductible | Depends on benefit rules |
| Changes with the service’s cost | Not as a percentage | Yes | Usually no |
When you read the health insurance coinsurance definition in a policy, look at the deductible listed for the same service. A 20% coinsurance rate tells only part of the story if you still have $1,500 left to pay toward your deductible.
Coinsurance vs Copays: Why the Difference Matters
The health insurance coinsurance vs copay difference is easiest to see with an example. A $30 copay generally stays $30 for the covered visit specified by your plan. In contrast, 20% coinsurance on a $200 allowed charge is $40, while 20% on a $2,000 allowed charge is $400.
Neither arrangement is always better. Your overall costs depend on the benefits you use, the premium you pay, and the plan’s cost-sharing rules. HealthCare.gov explains copayments and how they differ from other payments.
Health Insurance Coinsurance Definition and Out-of-Pocket Maximums
The health insurance coinsurance definition also needs to be understood alongside your plan’s out-of-pocket maximum. This limit generally caps what you pay for qualifying covered, in-network services during a plan year.
Deductibles, copays, and coinsurance for qualifying covered in-network care generally count toward that limit. Monthly premiums, noncovered services, and certain out-of-network charges generally do not.
For example, suppose your plan has a $3,000 deductible, 20% coinsurance, and a $6,000 in-network out-of-pocket maximum. If you receive $12,000 in eligible services and have not paid anything toward the deductible, you would pay $3,000 plus 20% of the remaining $9,000. Your total would be $4,800.
If later qualifying expenses bring your total to the $6,000 maximum, the plan generally pays 100% of covered in-network benefits for the remainder of that plan year. Learn more from HealthCare.gov’s out-of-pocket maximum guide.
Remember that family plans may have individual and family limits, so review both before estimating expenses.
How to Calculate Your Coinsurance Payment
The basic calculation is:
Your coinsurance = Allowed amount subject to coinsurance × Your coinsurance percentage
If your deductible is already met and the allowed amount is $750, a 20% coinsurance rate gives you a $150 payment. At 30%, your share would be $225.
Use these steps when estimating your own costs:
- Confirm that the service is covered under your policy.
- Ask whether the provider is in your insurance network.
- Find the insurer’s allowed amount or request an estimate.
- Check how much of the applicable deductible remains.
- Apply your coinsurance percentage to the amount subject to cost sharing.
- Check whether you are approaching your out-of-pocket maximum.
The health insurance coinsurance definition helps you perform the percentage calculation, but it does not guarantee your final bill. The insurer’s claim determination, coverage rules, and other cost-sharing provisions still matter.
Health Insurance Coinsurance Definition for In-Network Care
The health insurance coinsurance definition usually refers to a percentage of the insurer’s allowed amount for a covered service. In-network providers have agreed to certain payment terms with the health plan, which can make costs more predictable.
Out-of-network care may have a higher coinsurance percentage, a separate deductible, or no coverage at all. Depending on the situation, charges above the insurer’s allowed amount may also become your responsibility, subject to applicable surprise-billing protections.
Before scheduling nonemergency care, confirm the network status of the facility and relevant clinicians. If you receive an unexpected bill, compare it with your explanation of benefits and ask the insurer for clarification.
How to Compare Health Insurance Plans
The plan with the lowest coinsurance percentage is not automatically the least expensive. A policy with 10% coinsurance may charge a higher monthly premium or have a different deductible than one with 20% coinsurance.
Compare total expected yearly costs, including premiums, deductibles, copays, coinsurance, prescription drug expenses, and out-of-pocket limits. The HealthCare.gov guide to total costs explains why premiums alone do not tell the full story.
When evaluating options, understanding coinsurance can help you estimate how costs change if you need a specialist, imaging, surgery, or a hospital stay.
Review the Summary of Benefits and Coverage (SBC) for each plan. This standardized document helps you compare covered benefits, exclusions, and cost sharing.
Questions worth asking include:
- Is the coinsurance percentage different for primary care, specialists, hospital care, or prescription drugs?
- Does the deductible apply before coinsurance for each service?
- Are my preferred doctors and hospitals in network?
- Are there separate individual and family deductibles or out-of-pocket limits?
- What would I pay for a common procedure under each plan?
An insurance professional can help you understand these terms, but final coverage and claims decisions are governed by the insurance policy and carrier.
Health Insurance Coinsurance Definition: Common Mistakes
Even after learning the health insurance coinsurance definition, consumers can make costly assumptions. Watch for these common misunderstandings:
Mistake 1: Applying coinsurance to the provider’s full bill. For covered in-network care, the calculation generally uses the allowed amount rather than the original charge.
Mistake 2: Forgetting about the deductible. You may need to pay the remaining deductible before the coinsurance percentage applies.
Mistake 3: Assuming every service has the same percentage. Hospital care, outpatient procedures, office visits, and prescriptions may have different rules.
Mistake 4: Ignoring network restrictions. Out-of-network services can produce significantly different costs and coverage outcomes.
Mistake 5: Confusing the out-of-pocket maximum with your deductible. The deductible is one component of cost sharing; the maximum generally limits qualifying annual in-network spending.
Mistake 6: Choosing a plan based on coinsurance alone. Premiums, covered services, provider networks, and total financial exposure matter too.
Always pair this general explanation with your actual policy details; no single definition can promise what a particular service will cost.
Frequently Asked Questions About Coinsurance
What Does 20% Coinsurance Mean?
It generally means you pay 20% of the allowed amount for a covered service when coinsurance applies, and your insurer pays the remaining 80%. If the relevant deductible has not been met, your total payment may be higher.
Is Coinsurance Charged Before the Deductible?
Usually, coinsurance applies after you satisfy the deductible associated with that benefit. However, some services have different rules, so check your Summary of Benefits and Coverage.
Does 0% coinsurance mean healthcare is free? Not necessarily. You might still owe a deductible, copay, premium, or charges for services that are not covered.
Does coinsurance apply to prescription drugs? It can. Some plans use percentage-based drug costs, while others use copays, tiers, or separate pharmacy deductibles.
Does coinsurance reset every year? The percentage is a plan feature rather than a running balance. However, deductible and out-of-pocket accumulations generally reset at the start of the plan year, and your plan’s percentage can change at renewal.
Where can I find my coinsurance percentage? Check your SBC, policy documents, member portal, or explanation of benefits. You can also contact your insurer to confirm the percentage for a specific service.
Talk to HHAS Insurance About Coverage Options
Understanding the health insurance coinsurance definition is one step toward choosing coverage that fits your healthcare needs and budget. The right comparison also considers premiums, deductibles, network access, prescriptions, and potential out-of-pocket costs.
HHAS Insurance Services Inc. provides insurance guidance for individuals, families, and businesses. Explore its health insurance information and contact HHAS Insurance to discuss available options and questions about cost sharing.
Before enrolling, ask for plan-specific documents and confirm benefits, eligibility, availability, and pricing with the carrier. Coinsurance basics provide a useful starting point, but the terms of your actual policy determine what you owe.