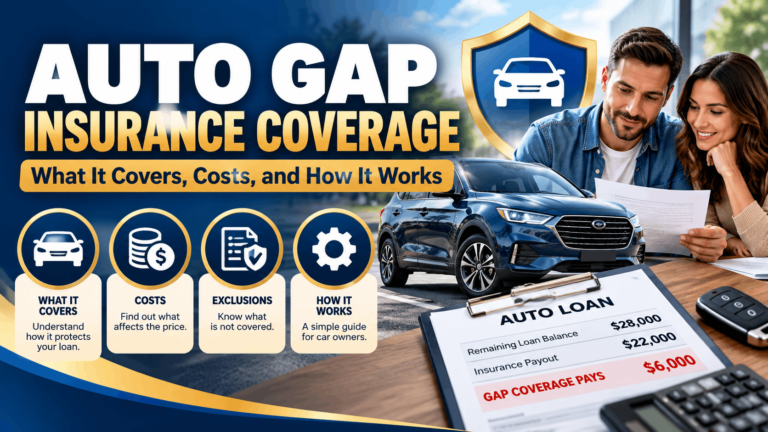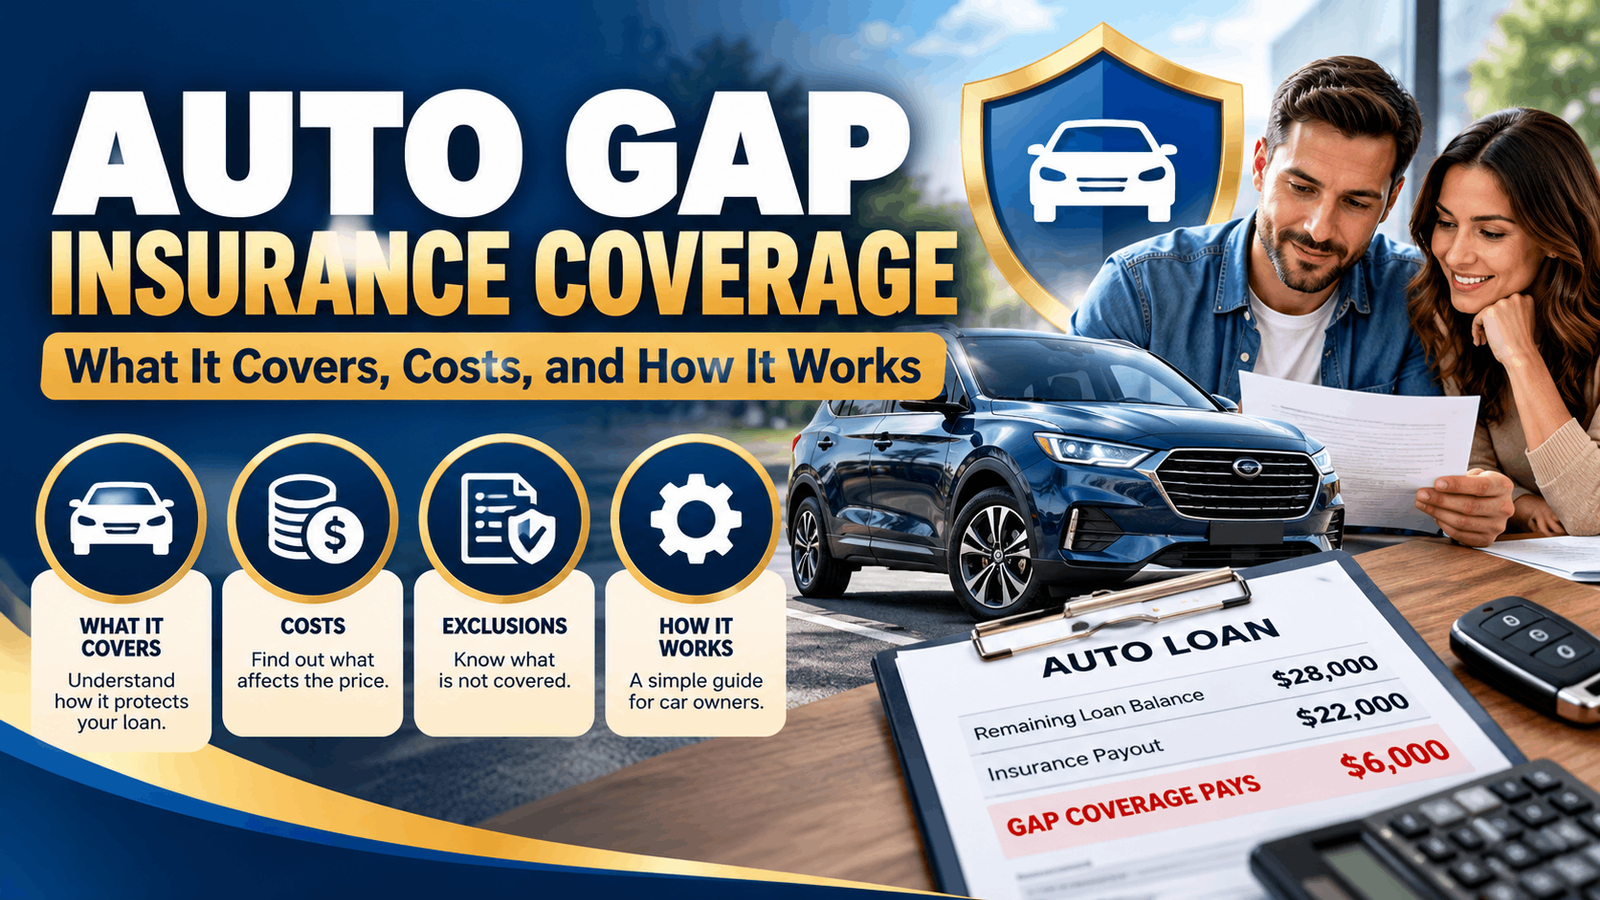
Auto gap insurance coverage can protect you from an unexpected loan balance if your financed or leased vehicle is stolen or declared a total loss. Your regular auto policy generally pays based on the vehicle’s value, not the amount you still owe. As a result, you could lose the car and still owe money to the lender.
However, GAP protection does not pay for every accident, repair, or remaining loan charge. Its benefits depend on your contract, the reason for the loss, and the amount your primary insurer pays. Before purchasing it, you should understand exactly what qualifies.
This guide explains how GAP works in the United States, what it covers and excludes, what affects its price, and when it may be worth buying.
What Is Auto Gap Insurance Coverage?
Auto gap insurance coverage helps address the difference between an eligible vehicle loan or lease balance and the amount paid by the primary auto insurer after a covered total loss. GAP commonly stands for Guaranteed Asset Protection. Some products are insurance policies, while others are GAP waivers that cancel a qualifying portion of debt. Although they serve a similar purpose, their terms and regulation may differ.
Consider a driver who owes more than a vehicle is worth. If the car is totaled, collision or comprehensive insurance generally bases the settlement on its actual cash value, subject to policy terms. The remaining loan balance does not automatically disappear.
The Consumer Financial Protection Bureau (CFPB) describes GAP as an optional product intended to address this shortfall. Therefore, it is particularly relevant when the amount owed exceeds the vehicle’s value.
Why a Loan Balance Can Exceed a Car’s Value
A vehicle’s market value and loan balance do not decline at the same pace. For example, a small down payment may leave you financing most of the purchase price. Longer loan terms can also mean the balance falls slowly, especially during the early years.
Additionally, rolling debt from a previous vehicle into a new loan may increase the amount owed. That does not mean every GAP contract will cover the rolled-over amount, however. Review the exclusions and maximum benefit before relying on the protection.
How Auto Gap Insurance Coverage Works
GAP becomes relevant when a qualifying total loss leaves an eligible loan or lease shortfall. First, your primary auto insurer evaluates the loss and determines the settlement under your policy. Next, the GAP provider reviews the remaining eligible balance and its contract terms.
A Simple GAP Insurance Example
Imagine these hypothetical figures after a covered total loss:
| Item | Amount |
|---|---|
| Remaining vehicle loan balance | $31,000 |
| Primary auto insurer’s settlement | $25,000 |
| Difference before GAP contract adjustments | $6,000 |
In this example, the potential shortfall is $6,000. A qualifying GAP product might pay or waive some or all of that eligible difference. However, deductibles, benefit caps, overdue payments, excluded loan charges, and other contract rules may change the final amount.
Without GAP, the borrower could remain responsible for the unpaid balance. With an eligible claim, the financial impact may be smaller. Either way, the lender or servicer should confirm the final account balance in writing.
What Does Auto Gap Insurance Coverage Cover?
GAP is designed for a narrow situation: an eligible total loss where the covered loan or lease balance is higher than the primary insurance settlement. Depending on the agreement, qualifying events may include a serious collision or theft when the vehicle is not recovered.
Total Loss After a Covered Collision
Collision insurance generally addresses covered damage from a crash. If the insurer declares the vehicle a total loss, GAP may address an eligible loan shortfall after the primary claim is settled. Nevertheless, the claim must meet both the auto policy’s and GAP agreement’s requirements.
Theft or Other Covered Comprehensive Loss
Comprehensive insurance generally covers certain noncollision events, including theft, subject to the policy. When a stolen vehicle is not recovered and the insurer settles it as a total loss, GAP may apply. By contrast, a minor theft-related repair does not normally trigger GAP benefits.
Leased Vehicles and Deductibles
Some leases include GAP protection or a waiver in the agreement. Others may offer it separately, so check the lease before paying for another product. In addition, certain GAP contracts may cover a limited amount of the primary policy’s deductible, while others do not.
Because these provisions vary, ask for the exact deductible treatment and any maximum payout in writing.
What GAP Insurance Does Not Cover
Car gap insurance coverage is not a replacement for collision, comprehensive, or liability insurance. It generally does not pay for ordinary repairs, maintenance, or a replacement vehicle simply because yours has lost value.
Common exclusions or limitations may include:
- Routine repairs, mechanical failures, and maintenance
- Loan payments due before the loss, late fees, or other excluded charges
- A deductible unless the contract specifically includes it
- Negative equity rolled over from an earlier loan, where excluded
- Amounts above the GAP benefit limit or loan-to-value cap
- Losses outside the required primary insurance coverage
- Vehicles or uses that do not meet eligibility rules
For instance, if your car needs $2,000 in repairs but is not totaled, GAP generally will not pay that repair bill. Likewise, a GAP contract does not automatically provide a down payment on your next car.
Read the exclusions carefully because an advertised promise to “cover the gap” may still have important limits.
Auto Gap Insurance Coverage Cost: What Affects the Price?
Gap insurance coverage cost depends on where you purchase it, how the product is structured, and the provider’s terms. Instead of assuming one nationwide price, compare actual offers for your vehicle, loan, and state.
You may encounter three common purchasing routes:
| Where You Buy | How It May Be Charged | What to Check |
|---|---|---|
| Auto insurer | An additional policy premium or endorsement charge | Eligibility, deductible rules, and cancellation terms |
| Dealer | Often a one-time add-on price, sometimes financed | Total price, interest, exclusions, and refund terms |
| Lender or credit union | A fee, waiver charge, or other product price | Whether coverage is already included and what it pays |
Why Financing GAP Can Increase Its Total Cost
Suppose a dealership offers a hypothetical $600 GAP product and adds that charge to your auto loan. You are not simply paying $600 in cash; you may also pay interest on the financed amount. Consequently, the total cost can exceed the original product price.
The CFPB advises comparing GAP prices and coverage before agreeing to an add-on. It also notes that financing the purchase increases the amount borrowed.
How Much Is GAP Insurance Coverage?
There is no single monthly or upfront cost that applies to every driver. Instead, request a written quote showing the full price, payment method, duration, and cancellation conditions. If a dealer offers a lump-sum product, compare that total with any eligible option available through your auto insurer or lender.
Who May Benefit From Car GAP Insurance Coverage?
GAP may be worth considering when you are likely to owe more than the car would be worth after a total loss. However, not every financed driver needs it.
Situations that may create a larger shortfall include:
- Making a small down payment
- Choosing a longer loan term
- Leasing a vehicle without GAP already included
- Financing a vehicle whose value may fall faster than the loan balance
- Carrying a high loan balance relative to the car’s current value
For example, someone with a short loan and a substantial down payment may have little or no shortfall. On the other hand, a borrower who owes considerably more than the car is worth may face a meaningful risk.
When You Might Not Need GAP
If your loan balance is already below the vehicle’s likely actual cash value, there may be no eligible difference for GAP to address. Similarly, someone who owns a car outright has no auto loan shortfall to protect.
Before deciding, compare a recent loan payoff statement with a realistic vehicle valuation. Keep in mind that the actual total-loss settlement is determined by the insurer under the policy, not by a valuation website alone.
GAP Insurance vs. Collision and Comprehensive Coverage
These products solve different problems. Collision and comprehensive insurance generally address covered physical damage to your vehicle, whereas GAP focuses on a qualifying financing shortfall after a total loss.
| Coverage | Main Purpose | Pays Off an Eligible Loan Shortfall? |
|---|---|---|
| Collision | Covered crash-related vehicle damage | Not by itself |
| Comprehensive | Certain covered noncollision losses, such as theft | Not by itself |
| GAP | Eligible difference between the loan or lease balance and primary settlement | May, subject to contract terms |
| New-car replacement | Certain eligible replacement costs under a separate endorsement | Not necessarily |
The NAIC’s auto insurance guide explains these coverage categories. Therefore, review your main auto policy before evaluating a GAP add-on.
Where Can You Buy GAP Coverage?
Drivers may find GAP products through an auto insurer, a dealership, a lender, or a credit union. Availability varies by state, vehicle, financing arrangement, and provider.
First, ask your current auto insurer whether it offers an eligible GAP option. Next, compare any dealer or lender proposal using the same loan details. Finally, check whether your lease already includes a waiver before purchasing duplicate protection.
According to the CFPB’s guidance on optional auto loan products, GAP is generally optional. If someone claims you must buy a particular add-on, ask them to show you the requirement in the relevant financing documents.
How to File a GAP Insurance Claim
After a total loss, contact both the primary auto insurer and the loan servicer. Because GAP claims depend on the underlying loss and financing details, the provider may need documents from each.
A practical process is:
- Report the loss. Open a claim with your primary insurer and obtain the claim number.
- Confirm the total-loss settlement. Request the insurer’s written settlement breakdown.
- Contact the GAP administrator. Ask for the claim instructions and deadlines.
- Gather loan documents. Provide the financing agreement, payoff information, and any required payment history.
- Track the remaining balance. Continue following your lender’s payment instructions until the servicer confirms the account is resolved.
Meanwhile, keep copies of emails, claim forms, and settlement notices. If a claim is denied, request the specific policy provision used to make that decision.
When to Cancel GAP and Ask About a Refund
You may no longer need GAP after paying off your loan, selling the vehicle, or refinancing into a situation where the product no longer applies. In addition, the protection may have little value once your loan balance is lower than the car’s value.
Cancellation and refunds depend on the agreement and applicable law. Some consumers may qualify for a refund of an unused portion of the product price after early payoff or cancellation. The CFPB explains these possible refund rights.
Therefore, review your paperwork and contact the provider, lender, or dealership for the exact process. Do not assume the cancellation or refund happens automatically.
How to Compare GAP Insurance Coverage Before Buying
A low price is useful only when the policy addresses your actual risk. Before signing, compare the following details:
- Eligible balance: Which loan or lease amounts count toward the shortfall?
- Benefit cap: Is there a maximum payment or loan-to-value limit?
- Deductible: Does the agreement cover any part of it?
- Exclusions: Are rolled-over debt, fees, or certain vehicle uses excluded?
- Primary coverage: Must you maintain collision and comprehensive insurance?
- Duration: When does GAP coverage begin and end?
- Cancellation: What refund, if any, is available if you pay off the loan early?
Also, ask whether the product is a GAP insurance policy or a debt-cancellation waiver. Although the goal may be similar, the contract and claim process can differ.
How HHAS Insurance Can Help You Review Auto Coverage
Understanding the relationship between your car’s value, your loan balance, and your auto insurance is an important first step. However, it is just as important to confirm which products are actually available for your vehicle and state.
HHAS Insurance Services Inc. provides auto insurance information and an auto insurance quote request. If you are reviewing your vehicle protection, you can also contact HHAS Insurance to discuss your needs and ask about available options.
Specific GAP products are not guaranteed to be available through HHAS; availability depends on the provider and eligibility requirements.
Frequently Asked Questions About GAP Insurance Coverage
What Is GAP Insurance Coverage on a Car?
It is optional protection intended to address an eligible difference between the loan or lease balance and the primary insurer’s payment after a covered total loss. However, contract limits and exclusions determine the actual benefit.
Does GAP Pay if My Car Is Damaged but Not Totaled?
Generally, no. GAP is meant for an eligible total loss, not ordinary repairs. Instead, collision or comprehensive insurance may address covered physical damage under your main auto policy.
Does GAP Cover My Auto Insurance Deductible?
Some agreements cover a limited deductible amount, but others exclude it. Therefore, check the contract before assuming the deductible will be paid.
Is GAP Required for a Financed Car?
GAP is generally an optional add-on rather than a universal requirement. However, review your specific loan or lease agreement and ask the lender to identify any contractual condition.
Can I Get a GAP Refund After Paying Off My Car?
Possibly. Refund rights depend on the product, timing, contract, and state rules. Consequently, contact the administrator or lender and ask for the cancellation and refund calculation.
Is Automobile GAP Insurance Coverage the Same as Regular Auto Insurance?
No. Automobile GAP insurance coverage addresses a qualifying loan or lease shortfall, while standard auto insurance provides the protections you select, such as liability, collision, and comprehensive coverage. Both should be reviewed separately.
Final Thoughts on Auto Gap Insurance Coverage
Auto gap insurance coverage can be valuable when your vehicle loan exceeds the amount your insurer would pay after a covered total loss. Nevertheless, it is not a replacement for comprehensive or collision insurance, and it does not automatically erase every outstanding loan charge.
Before buying, compare your loan balance with your car’s likely value, read the exclusions, and check whether you already have GAP through a lease or financing agreement. Ultimately, the right choice depends on your financial exposure and the terms of the available product.
To review your current auto protection, explore HHAS Insurance’s auto insurance services or request an auto insurance quote.z