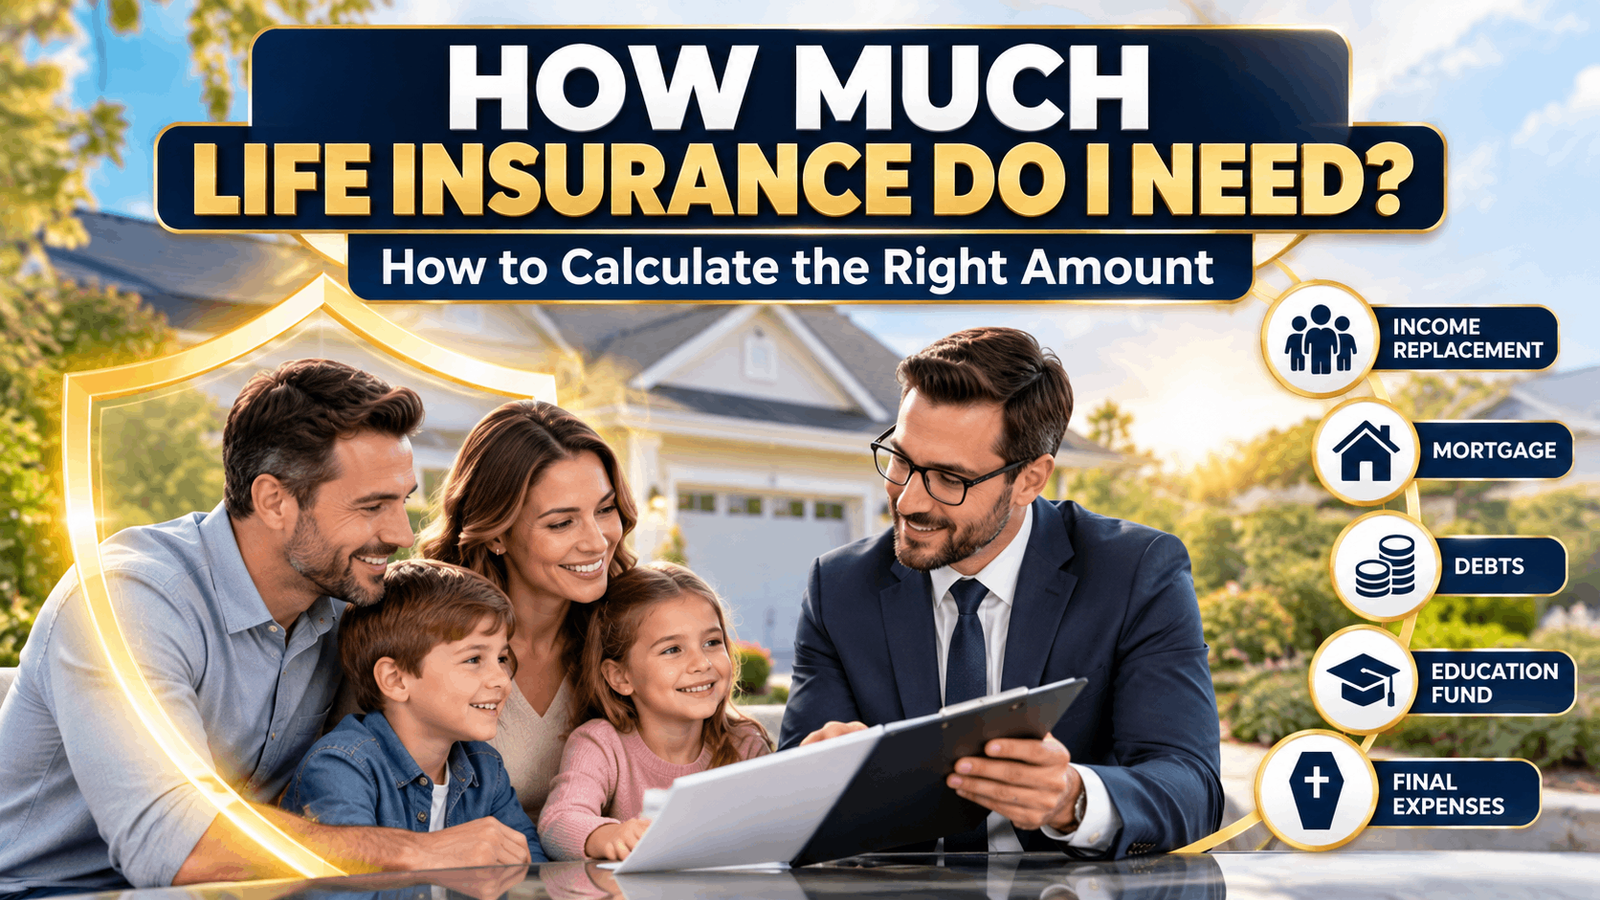
How Much Life Insurance Do I Need? How to Calculate the Right Amount
If you are asking how much life insurance do I need, there is no single coverage amount that works for every person or family. Your income, debts, dependents, mortgage, savings, existing life insurance, and future financial responsibilities can all affect the answer.
Therefore, the most useful approach is not to choose a round number or rely only on a salary multiple. Instead, estimate the financial gap your family or other dependents could face if you were no longer there to provide income, services, or financial support.
The National Association of Insurance Commissioners (NAIC) recommends considering factors such as family income, financial dependents, debts, final expenses, children’s education, existing coverage, and future needs when deciding how much life insurance may be appropriate. NAIC Content
HHAS Insurance Services Inc. also offers life insurance and explains several policy types, including term, whole, universal, and variable universal life insurance. hhasinsurance.com You can review the HHAS Life Insurance page as you consider your options.
How Much Life Insurance Do I Need? Start With Your Financial Responsibilities
A life insurance calculation should begin with the people and obligations that depend on you financially.
For example, a parent supporting young children may need to consider many years of income replacement. Meanwhile, someone approaching retirement may have fewer working years to replace but could still have a mortgage, spouse, dependent family members, business obligations, or other financial goals.
Start by considering:
- Income your household would lose
- Mortgage or housing obligations
- Credit cards, personal loans, and other debts
- Financial support for a spouse or partner
- Costs associated with raising children
- Future education goals
- Final expenses
- Support for aging parents or other dependents
- Existing life insurance
- Savings and other assets available to survivors
- Employer-provided life insurance
- How many years financial support may be needed
The NAIC similarly encourages consumers to ask how much family income they provide, who depends on them financially, how survivors would handle debts and final expenses, and whether current employer coverage is enough. NAIC Content
As a result, your life insurance amount should reflect your actual financial situation rather than another person’s coverage.
A Simple Way to Calculate Your Life Insurance Needs
One practical way to estimate coverage is to compare your family’s potential financial needs with the resources they would already have available.
You can begin with this simple framework:
Estimated coverage need = income replacement + debts + future financial needs + final expenses − existing financial resources
This is an estimate rather than a universal insurance formula. However, it can help organize the major factors that matter.
Step 1: Estimate Income Replacement
First, consider how much of your income your household depends on.
Then think about how long that support might be needed.
For example, a household with young children may want to consider a longer support period than a household in which both spouses are close to retirement.
However, replacing income does not always mean multiplying your current salary by a fixed number. Your family’s needs may change over time, so consider both the amount and duration of support.
Step 2: Add Outstanding Debts
Next, review financial obligations that could affect your family.
These may include a mortgage, vehicle loans, credit cards, personal loans, or other debts.
However, not every debt necessarily needs to be covered dollar for dollar. The important question is how each obligation would affect the people you want to protect.
Step 3: Consider Future Expenses
After reviewing current obligations, think about future financial needs.
For parents, education may be one consideration. In addition, a family might want funds available for childcare, housing, or other long-term needs.
The NAIC specifically recommends considering whether children may need money for education and how survivors would manage financially after the insured person’s death. NAIC Content
Step 4: Consider Final Expenses
Your calculation can also account for expenses your family may face after your death.
Instead of using a universal estimate, decide what amount makes sense for your own circumstances and plans.
Step 5: Subtract Existing Resources
Finally, consider financial resources that may already be available.
For example, these could include existing individual life insurance, employer-sponsored coverage, and assets that you specifically intend to make available for family needs.
However, be careful about automatically counting every asset. Retirement accounts, emergency savings, and other investments may already serve different financial goals.
The result gives you a starting estimate rather than a final recommendation.
Life Insurance Calculation Example
Consider a hypothetical household in which one person wants to estimate the financial gap their family might face.
Suppose that person determines that the family would need:
$700,000 for future income support
$250,000 to address the mortgage and other debts
$150,000 for future family and education goals
$25,000 for other anticipated end-of-life needs
Their estimated needs would total $1,125,000.
Now suppose they have $200,000 of existing life insurance and $125,000 in assets they have specifically decided could be used for these needs.
Subtracting $325,000 from $1,125,000 would leave an estimated financial gap of $800,000.
That does not mean $800,000 is the right amount for everyone in that situation. Instead, the example demonstrates how a needs-based calculation can work.
Your own numbers could produce a very different result.
Using a How Much Life Insurance Do I Need Calculator
Someone searching for a how much life insurance do I need calculator is usually looking for a faster way to organize these numbers.
A useful calculator should consider more than income alone.
Ideally, your estimate should account for income replacement, debts, mortgage obligations, future family needs, existing life insurance, and financial resources that could realistically be available to survivors.
However, calculators are still estimates. They cannot fully understand your family’s priorities, future plans, business interests, or changing financial situation.
Therefore, use a calculator as a starting point rather than treating its result as an automatic coverage recommendation.
The NAIC Life Insurance Consumer Resource provides questions consumers can use when evaluating their life insurance needs and policy options. The NAIC also publishes a Life Insurance Buyer’s Guide that discusses estimating coverage based on individual needs. NAIC Content
How Much Life Insurance Do I Need Rule of Thumb?
The phrase how much life insurance do I need rule of thumb often leads to recommendations based on multiplying annual income by a fixed number.
Rules of thumb can provide a quick starting point. However, they can also miss important details.
The NAIC notes that some insurance experts suggest using an income multiple, but it recommends working through your actual financial obligations to reach a more accurate estimate. NAIC Content
For example, two people earning the same salary could have completely different needs.
One might have three children, a mortgage, and a spouse who depends heavily on their income. Meanwhile, the other might be single, have substantial savings, and carry little debt.
Using the same salary-based calculation for both could produce an estimate that does not reflect either person’s full situation.
Therefore, an income rule can be a useful checkpoint, but a needs-based calculation is usually more informative.
Consider the DIME Method as Another Starting Point
Another commonly discussed approach is the DIME method.
DIME stands for:
Debt
Income
Mortgage
Education
The method asks you to consider these four major financial categories when estimating coverage. Several life insurers describe DIME as a way to organize financial obligations when estimating life insurance needs. Protective
However, DIME does not automatically account for every household factor.
For example, it may not fully capture existing life insurance, available assets, support for aging parents, unpaid caregiving, business obligations, or other personal goals.
Therefore, you can use DIME as a framework while still adjusting the calculation for your circumstances.
How Much Life Insurance Do I Need If I’m Single?
The question how much life insurance do I need if I’m single does not always have an answer of zero.
First, consider whether anyone depends on you financially.
You might help support a parent, sibling, child, partner, or another person even if you are unmarried. In addition, you may have financial obligations that could affect someone else.
For example, consider whether you have jointly held debt, co-signed obligations, business commitments, or other financial responsibilities.
On the other hand, a single person with no dependents, limited obligations, and sufficient assets may have a smaller life insurance need than someone supporting a family.
Therefore, marital status alone should not determine your coverage amount.
How Much Life Insurance Do I Need for My Spouse?
When asking how much life insurance do I need for my spouse, income is only one part of the calculation.
A spouse who earns a salary may contribute directly to household income. However, a spouse who does not receive a paycheck may still provide significant household value through childcare, transportation, household management, caregiving, or other responsibilities.
If those services suddenly had to be replaced, the surviving household could face new expenses.
Therefore, when estimating coverage for either spouse, consider both financial income and the practical services each person contributes.
Also review shared debts, mortgage obligations, children’s needs, future goals, and the surviving spouse’s ability to maintain the household.
How Much Life Insurance Do I Need for My Child?
Parents searching how much life insurance do I need for my child are dealing with a different question from income replacement for an adult.
Children generally are not household wage earners. Therefore, the purpose of coverage is different.
Before purchasing a policy, consider why you want the coverage, what financial need you are trying to address, and whether another financial product may better fit that goal.
In addition, policy features and long-term objectives can vary considerably among life insurance products.
Because this decision can involve both insurance and long-term financial planning, parents should review the policy carefully and understand its purpose, premiums, guarantees, exclusions, and other terms before buying.
How Much Life Insurance Do I Need at 60?
The question how much life insurance do I need at 60 should be approached differently from the same question at age 30.
By age 60, some people may have fewer years of employment remaining. In addition, children may be financially independent, and a mortgage may be smaller or fully paid.
However, that does not mean life insurance is automatically unnecessary.
You may still have a spouse who depends on your income, outstanding debt, a mortgage, business obligations, estate planning goals, dependent family members, or other financial responsibilities.
Therefore, review what has changed rather than relying on the amount you needed earlier in life.
The NAIC recommends reviewing insurance needs over time because financial obligations and the period during which death benefits may be needed can change. NAIC Content
Don’t Forget Employer Life Insurance
Many Americans receive some life insurance through work.
That coverage can be valuable. However, you should compare the death benefit with your actual financial needs rather than assuming workplace coverage is sufficient.
The NAIC Life Insurance Buyer’s Guide specifically advises consumers to consider whether employer-provided life insurance is enough to meet their financial obligations. It also notes that workplace coverage may not always remain with you after leaving an employer. NAIC Content
Therefore, include employer coverage in your calculation, but also understand its amount, terms, and portability.
Existing Savings Can Change the Amount You Need
Life insurance is intended to address a financial need. As a result, existing resources matter.
For example, a household with significant liquid assets may calculate a different insurance gap from a household with the same income but limited savings.
However, avoid subtracting assets automatically.
Ask whether those funds would genuinely be available for the purpose you are calculating. A retirement account intended to support a surviving spouse for decades, for example, may already have an important job.
Instead, identify which assets you reasonably expect survivors to use for the obligations included in your calculation.
Term vs. Permanent Insurance: Coverage Amount and Policy Type Are Separate Decisions
After estimating how much coverage you need, you still need to consider what type of life insurance fits your goals.
HHAS explains several life insurance options, including term life, whole life, universal life, and variable universal life. hhasinsurance.com
Term insurance generally provides coverage for a specified period. Meanwhile, permanent forms of insurance can be designed to remain in force longer and may include cash-value features, depending on the policy.
The NAIC also distinguishes between term insurance and cash-value insurance and advises consumers to consider how long they need coverage and what they can afford. NAIC Content
Therefore, first determine the financial need. Then evaluate which policy structure can address that need at a cost you can reasonably maintain.
You can learn more about available policy categories on the HHAS Life Insurance page.
Review Your Coverage After Major Life Changes
The amount of life insurance that fits your needs today may not be appropriate ten years from now.
For example, consider reviewing your coverage after:
- Marriage or divorce
- Birth or adoption of a child
- Buying or selling a home
- A major income change
- Starting or selling a business
- Taking on significant debt
- Paying off a mortgage
- Children becoming financially independent
- Retirement
- Major changes to your savings or investments
As your obligations decline, your coverage needs may decrease. However, new responsibilities can also increase the financial gap you want insurance to address.
Therefore, life insurance planning should be treated as an ongoing process rather than a one-time calculation.
Don’t Cancel Existing Coverage Too Quickly
If you already have life insurance and are considering a replacement, avoid canceling the existing policy before the new coverage is fully in place.
The NAIC specifically advises consumers not to cancel an existing policy until they have received the new policy. Changes in health can affect eligibility or the premium for new coverage. NAIC Content
In addition, compare the features, costs, guarantees, exclusions, surrender implications, and other terms of both policies.
Replacing life insurance can have important consequences. Therefore, make the decision based on the complete policy details rather than premium alone.
Life Insurance and Federal Taxes
Tax treatment is another topic consumers sometimes consider when planning life insurance.
According to the IRS, life insurance proceeds received by a beneficiary because of the insured person’s death are generally not included in gross income. However, exceptions can apply, and interest received may be taxable. IRS
For current federal information, review the IRS guidance on life insurance proceeds.
Because individual tax situations can differ, consult a qualified tax professional when you need advice about your specific circumstances.
Questions to Ask Before Choosing a Coverage Amount
Before deciding on an amount, ask yourself whether your estimate accounts for your real financial responsibilities.
Consider who depends on your income, how long they may need support, which debts matter, what future expenses you want to fund, and what resources are already available.
Next, think about affordability. A coverage amount only works if the policy fits your budget well enough to keep it in force according to its terms.
Finally, understand what you are buying. Compare the policy type, death benefit, premium structure, guarantees, exclusions, riders, and other relevant terms before making a decision.
Frequently Asked Questions
How much life insurance do I need?
There is no universal amount. Start by estimating income your dependents may need, debts, mortgage obligations, future expenses, and other financial responsibilities. Then subtract existing coverage and resources you reasonably expect to be available for those needs.
Is there a simple life insurance calculator formula?
A useful starting framework is to add income replacement, debts, future financial needs, and final expenses, then subtract relevant existing resources. However, the result is only an estimate and should be adjusted for your circumstances.
What is a good life insurance rule of thumb?
Income multiples are commonly used as shortcuts. However, the NAIC recommends looking more closely at family income, dependents, debts, final expenses, education needs, and other obligations when estimating coverage. NAIC Content
Should I include my mortgage in my calculation?
If paying the mortgage would create a financial burden for the people you want to protect, it may be appropriate to include some or all of that obligation in your needs analysis.
Do I need life insurance if I’m single?
Possibly. Consider whether anyone depends on you financially and whether you have shared debts, co-signed obligations, business responsibilities, or other financial commitments. Someone without dependents or significant obligations may calculate a smaller need.
Should both spouses have life insurance?
It can be useful to evaluate each spouse separately. In addition to income, consider childcare, caregiving, household management, and other services that could cost money to replace.
How does age affect how much coverage I need?
Your financial responsibilities often change with age. For example, income-replacement needs may decline as you approach retirement, while other obligations may remain. Therefore, calculate your current needs rather than relying on an amount chosen years earlier.
Is life insurance through work enough?
It depends on the amount and your financial obligations. The NAIC recommends comparing employer-provided coverage with the amount your family would actually need. NAIC Content
Should I subtract savings from my life insurance calculation?
You can consider assets that you genuinely intend to make available for survivors’ financial needs. However, be careful not to count assets that already serve another important purpose.
How often should I review my life insurance?
Reviewing coverage after major financial or family changes can help keep the amount aligned with your current needs. Marriage, children, a new home, retirement, business changes, and major debt changes are all useful review points.
Calculate the Right Amount for Your Situation
So, how much life insurance do I need? The answer should come from your financial responsibilities rather than an arbitrary number.
Start with the income your household may need. Then add relevant debts, housing obligations, future family expenses, and other financial goals. Afterward, subtract existing coverage and assets that you reasonably expect to be available.
Most importantly, review the result in the context of your budget and the people you want to protect.
HHAS Insurance Services Inc. provides life insurance information and quote options. Its website states that the agency is licensed in California, Arizona, Michigan, Oregon, and Texas. hhasinsurance.com
You can explore HHAS Life Insurance or use the verified HHAS Life Insurance Quote form to begin reviewing available options.