The Auto Insurance Every Driver Should Have.
Did you know nearly 14% of drivers in the U.S. are uninsured? This is a big problem. Auto insurance is more than just a law; it’s a safety net for our finances on the road. Knowing what auto insurance you need is key to avoiding big financial losses. Every state has its own rules for auto insurance. You usually need to have liability insurance to protect others if you cause an accident. But, just meeting the minimum might not be enough. In this article, we’ll explore the different types of auto insurance you need to stay safe and worry-free on the road. Key Takeaways Auto insurance is vital for protecting yourself and others. Knowing your state’s rules helps you meet the legal minimums. Adding coverages like collision and comp can offer more protection. Being informed helps you pick the right coverage for your needs. Auto insurance is not just for safety; it’s also for financial security. Understanding the Importance of Auto Insurance Auto insurance is a must for every driver. It acts as a financial shield against accidents. Many states require car insurance, focusing on basic liability coverage. This coverage protects against injuries and property damage if you’re at fault. But, these minimums might not protect your assets fully. If your coverage is too low, you could face big costs. This could harm your finances, home, and savings. It’s key to choose insurance that protects your financial health. Car insurance does more than meet legal needs; it gives you peace of mind. With the right coverage, you can drive without worry. It’s about keeping you safe and financially secure. Auto Insurance Coverage Every Driver Needs It’s key to know about the different auto insurance coverages. These coverages help protect us financially and give us peace of mind. We’ll look at the main types of coverage every driver should think about. Liability Coverage: Protecting Yourself and Others Liability coverage is a must-have in auto insurance. It helps cover costs for injuries or damages we might cause to others or their property. Most states require a certain level of liability coverage, so it’s very important. Collision Coverage: Repairing Your Car After an Accident Collision coverage is vital for fixing your car after an accident. It doesn’t matter who’s at fault. This coverage ensures your car gets fixed fast. It helps avoid long waits for another party’s insurance to pay. Comprehensive Coverage: Coverage Beyond Collisions Comprehensive coverage protects against many non-collision incidents. It covers theft, vandalism, natural disasters, and more. With this coverage, we know our car is safe from many risks, not just accidents. Uninsured Motorist Coverage: A Necessity on the Road Uninsured motorist coverage is often overlooked but is very important. It helps if you’re in an accident with someone who doesn’t have enough insurance. This coverage makes sure we don’t have to pay for medical bills or repairs ourselves. Adding these insurance types to our policy makes driving safer. They help us deal with damages from others and unexpected events. These coverages create a strong safety net for us. Exploring Optional Auto Insurance Coverages Auto insurance has many parts, and optional coverages are key. They add extra security and peace of mind. These coverages are more than just basics. Personal Injury Protection (PIP) Explained Personal injury protection, or PIP, pays for medical costs and lost wages after an accident. It doesn’t matter who caused the accident. This is very helpful in states with no-fault laws. With PIP, we can get the medical care we need right away. It helps us and our passengers avoid big medical bills. Rental Car Reimbursement: Staying Mobile After an Accident Rental car reimbursement helps when our car is in the shop. It lets us keep moving without extra costs. This is great for work or family needs. It keeps us independent and lets us keep up with our daily lives. We don’t have to stop because of an accident. Roadside Assistance: Peace of Mind on Every Journey Roadside assistance is a must-have for any driver. It offers peace of mind on the road. It covers towing, tire changes, fuel delivery, and more. When our car has a problem, roadside assistance is there. It means we’re never stuck, and we can stay calm until help comes. Factors That Influence Auto Insurance Premiums Auto insurance can be confusing. Knowing what affects our premiums helps us save money. Several key factors play a big role in these rates. Driving Record and Claims History Your driving history is very important to insurance companies. A clean record means lower premiums. But, accidents or tickets can raise your rates because you’re seen as a higher risk. Vehicle Type and Usage The car you drive affects your insurance costs. Fast or fancy cars cost more because they’re pricier to fix and steal. But, sedans and family cars are often cheaper. How you use your car also matters, like for work or fun. Location and Its Impact on Premium Rates Where you live changes your insurance rates. Cities have higher rates because of more traffic and theft. But, living in the country might mean lower premiums because it’s safer. Knowing this helps you guess your premium better. Factor Impact on Premiums Driving Record Clean record leads to lower premiums; violations increase rates. Vehicle Type Luxury and sports cars have higher costs; safer cars lower rates. Location Urban areas usually result in higher premiums; rural areas are often lower. Choosing the Right Coverage for Your Needs Choosing auto insurance coverage is a big decision. We need to think about our lifestyle, how often we drive, and what we can afford. It’s also important to know the state requirements, as they vary and can affect our choices. Assessing Your Coverage Needs Based on Lifestyle Our lifestyle affects the auto insurance we need. For example, people who drive a lot might want more liability coverage. Those who drive less might choose basic coverage. Understanding our driving habits helps us make the right choice. Understanding State-Specific
Liability vs Full Coverage Auto Insurance: Choosing the Right Policy
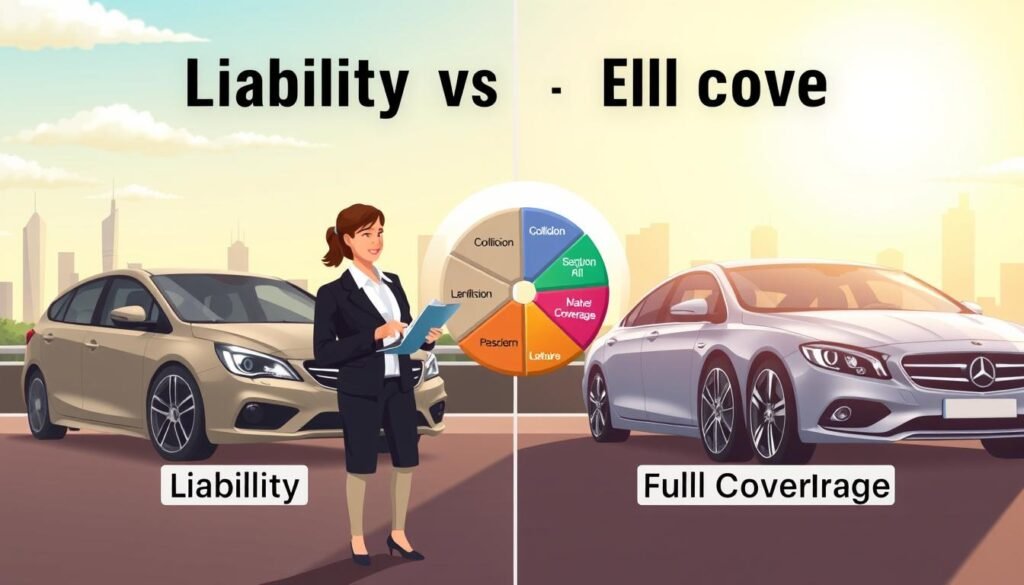
Did you know that about 31% of American drivers don’t have insurance? This fact shows how vital it is to know about auto insurance options. It’s not just about following the law; it’s about keeping your finances safe and feeling secure when unexpected things happen. Understanding the difference between liability and full coverage auto insurance is key. This knowledge helps protect your car and your money. We’ll explore the main points of each coverage type. This way, you can make a smart choice that fits your needs. Key Takeaways Understanding your auto insurance options is critical for financial security. Liability insurance covers damages to others, while full coverage includes additional protections. Knowing the differences in coverage can help you avoid costly mistakes. Assess your own needs and situation to determine the best policy type. Uninsured drivers highlight the importance of having adequate coverage. Understanding Auto Insurance Basics Knowing the basics of auto insurance is key to picking the right policy. Auto insurance has different types of coverage. Liability insurance is a must in most states. What is Liability Insurance? Liability insurance helps protect us from claims for damages we cause to others or their property. It’s a basic requirement by law. But, it doesn’t cover our own vehicle or injuries we might get in an accident. What is Full Coverage Insurance? Full coverage insurance goes beyond liability. It includes collision and comprehsensive coverage. This gives us a wider safety net. It covers our responsibilities to others and our own vehicle’s risks. Liability vs Full Coverage Auto Insurance Explained Knowing the difference between liability and full coverage auto insurance helps us choose wisely. Each type has its own role in protecting us. Liability insurance covers damages we might cause to others. Full coverage, on the other hand, includes both liability and costs for fixing or replacing our vehicle. Key Differences in Coverage The coverage differences are key to our financial safety. Here’s a table that shows the main differences: Feature Liability Insurance Full Coverage Insurance Protection for Others Yes Yes Vehicle Repair Costs No Yes Replacement Costs for Your Vehicle No Yes Types of Coverage Included Only mandatory liability coverage Includes collision and comprehensive coverage Default for Most States Yes No Why Insurance Terminology Matters Understanding insurance terms is critical when comparing liability vs full coverage auto insurance explained. Terms like “collision” and “comprehensive” can be confusing. Knowing these terms helps us choose the right policy for our budget and needs. What Does Liability Insurance Cover? It’s key to know what liability insurance covers to make smart choices about your auto insurance. Liability insurance helps protect us from financial losses due to accidents. It’s split into different types to handle different situations. Types of Liability Coverage Liability insurance has two main types: Bodily Injury (BI) Liability: This covers costs for injuries to others if we’re at fault in an accident. It pays for medical bills, lost wages, and sometimes pain and suffering. Property Damage (PD) Liability: This handles damage to another person’s property due to our actions. It can pay for their vehicle repairs or other accident-related costs. What is Not Covered by Liability Insurance? It’s also vital to know what liability insurance doesn’t cover. Knowing these exclusions can prevent surprises after an accident. Key exceptions include: Damage to our own vehicle, which isn’t covered by liability insurance. Other types, like collision or comp insurance, are needed for this. Medical costs for ourselves or our passengers in our vehicle. Liability insurance doesn’t cover our medical expenses after an accident. Knowing these limits shows why it’s important to review our coverage and maybe get more insurance. This ensures we’re fully protected on the road. What Does Full Coverage Insurance Include? It’s important to know what full coverage insurance covers. It includes collision and comprehensive coverage. These parts work together to protect our vehicles well. Collision Coverage Explained Collision coverage is a big part of full coverage insurance. It helps pay for car repairs after an accident, no matter who’s to blame. This way, we don’t have to spend a lot of money to fix our car. It covers damage from hitting another car or object. So, if we crash, collision coverage helps us financially. Comprehensive Coverage Explained Comprehensive coverage is another essential part of full coverage insurance. It protects our car from damage not caused by accidents. This includes theft, vandalism, and damage from natural disasters. With this coverage, we can feel safe knowing our car is protected from many dangers. Cost Comparison: Liability vs Full Coverage Knowing the cost difference between liability and full coverage is key. Each has its own pros and cons, mainly affecting insurance prices. We need to look at what affects these costs to plan our budgets better. How Factors Affect Insurance Premiums Many things influence insurance costs. Key factors include: Driving history: A clean record means lower premiums. Vehicle type: Expensive cars cost more. Geographical location: High-risk areas raise premiums. Understanding these factors helps us see how they affect costs. This is important when comparing liability and full coverage. Average Cost of Each Coverage Type Insurance costs vary a lot. Full coverage is usually three to five times more expensive than liability-only. For example: Coverage Type Average Annual Premium Liability Insurance $500 Full Coverage Insurance $1,500 This big price gap makes choosing wisely very important. Knowing the average costs helps us make smart financial choices. We aim for both protection and affordability. Do You Need Full Coverage Insurance? Deciding if you need full coverage insurance is a big decision. It depends on many personal factors. It’s important to understand what’s best for you. Factors to Consider When Choosing Coverage There are several things to think about when deciding on insurance. First, look at your car’s age and value. If your car is new or expensive, full coverage is a good idea. It helps protect you from big financial losses. But, if your car is old and not worth much, you might only need liability insurance.